
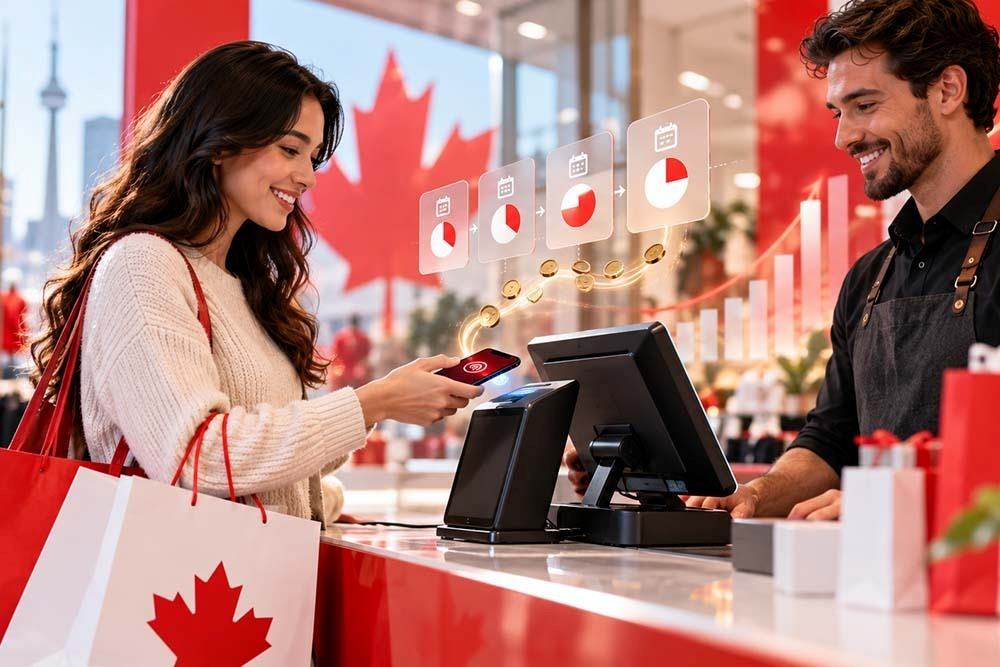
Buy now, pay later has become a mainstream retail payment option. For merchants evaluating buy now pay later Canadian retail 2026, the decision is not simply about adding another checkout button. BNPL can influence conversion, average order value, fees, refunds, and cash timing. The right approach depends on margins, customers, sales channels, and provider terms.
How BNPL Works for Retailers
With BNPL, the customer finances a purchase through a provider while the retailer is paid according to the provider’s settlement terms. The provider then collects instalments from the customer. This can make BNPL for Canadian retailers attractive because merchants need not wait for every instalment before settlement.
However, merchant fees may be higher than standard card costs. Businesses should compare transaction fees, fixed charges, refund treatment, disputes, settlement timing, integrations, and contract terms before launching.
Should Your Store Offer BNPL?
Retailers asking should my store offer buy now pay later Canada should start with customer behaviour. BNPL may be useful when products have a higher ticket, customers are price-sensitive, or shoppers abandon carts because of the upfront cost.
It may be less compelling for low-margin products where fees reduce profit. Before adopting buy now pay later Canadian retail 2026, model the effect on gross margin after provider fees and expected changes in order size.
The Financial Consumer Agency of Canada describes BNPL as a form of credit and warns consumers that missed payments, fees, or other borrowing costs may apply under the plan. Retailers should present payment options clearly.
Cash Flow Implications
One advantage of BNPL for Canadian retailers is that payment timing can be more predictable than extending store credit directly. In many arrangements, the BNPL company handles customer repayment risk while the merchant receives funds under agreed terms.
That does not mean BNPL always improves cash flow. A higher transaction fee can reduce contribution margin, while returns may create deductions or reconciliation work. Finance teams should compare net cash from BNPL orders with other payment methods.
For a business asking should my store offer buy now pay later Canada, the key calculation is incremental gross profit after fees, returns, marketing costs, and operational expenses.
BNPL Providers in Canada
Afterpay and Klarna are recognizable names in Canada. Afterpay promotes in-store and ecommerce options for retailers in Canada, while Klarna expanded its Canadian retail presence, including a Walmart Canada rollout in 2025.
When comparing Afterpay Klarna Canadian retailers 2026 options, merchants should review integration compatibility, channels, settlement schedules, pricing, eligibility, refunds, and support.
Other payment platforms may offer instalment or financing features, so the best fit depends on your ecommerce platform, POS system, and customer.
Can BNPL Increase Average Order Value?
Providers often market BNPL as a tool that can increase conversion and basket size. Afterpay states that retailers offering its in-store service have seen higher units per transaction and average order value. Those figures are provider-reported and may not apply to every business.
The effect of buy now pay later Canadian retail 2026 will vary by category, price point, season, and customer mix. Merchants should test where possible and compare conversion rate, average order value, return rate, fees, and profit per order.
A higher average order value is only valuable when it produces higher profitable revenue.
How to Evaluate BNPL Before Launching
Businesses considering BNPL for Canadian retailers should request pricing and settlement details. Review deposit timing, disputes, refund treatment, and minimums or termination obligations.
When assessing Afterpay Klarna Canadian retailers 2026, also check whether the provider supports online and in-store transactions if omnichannel consistency matters.
The strongest answer to should my store offer buy now pay later Canada comes from your own numbers. Test the payment method, track results, and compare net profitability instead of judging success only by increased sales.
FAQs
Q1: Should a Canadian retailer offer buy now pay later to customers?
A: It can be useful for retailers with suitable margins and customers who value instalment payments. Compare provider fees, settlement terms, customer demand, and expected profit before deciding.
Q2: How does buy now pay later affect merchant cash flow in Canada?
A: The provider may settle the merchant before collecting all customer instalments, depending on the agreement. This can support predictable cash flow, but fees, refunds, and settlement timing still affect net cash.
Q3: What BNPL providers work with Canadian retail businesses?
A: Afterpay Klarna Canadian retailers 2026 operate in the market. Retailers should also check ecommerce and payment platforms for additional financing integrations.
Q4: Do buy now pay later options increase average order value for Canadian retailers?
A: They can. Provider data suggests BNPL may increase basket size, but results vary. Merchants should measure their own conversion, order value, returns, fees, and profit before treating higher sales as a financial benefit.